Contents
Key Summary
2026-09-18 Current view: I am late. The market cap is under $0.1B now, it is heading for bankruptcy, and the borrow fee is cheap on top of that. I have not done much in-depth research or study, so I am just putting on a tiny short casually.
2026-09-18 Current Position:
| Ticker | Total Shares | Average Cost | Current Price | Gain | Return | Exposure | Weight |
|---|---|---|---|---|---|---|---|
| EVTL | -1,617.00 | 1.70 | 0.62 | 1,746.36 | 63.53% | -1,002.54 | -0.07% |
2026-09-18 Trade Record:
| Date | Ticker | Action | Shares | Total | Execution Price | Weight Before | Weight After |
|---|---|---|---|---|---|---|---|
| 2026-06-30 | EVTL | Short | -1,617.00 | 2,748.8 | 1.70 | -0.20% |
Complete Notes
Created the Note
Current Position:
| Ticker | Total Shares | Average Cost | Current Price | Gain | Return | Exposure | Weight |
|---|---|---|---|---|---|---|---|
| EVTL | -1,617.00 | 1.70 | 0.62 | 1,746.36 | 63.53% | -1,002.54 | -0.07% |
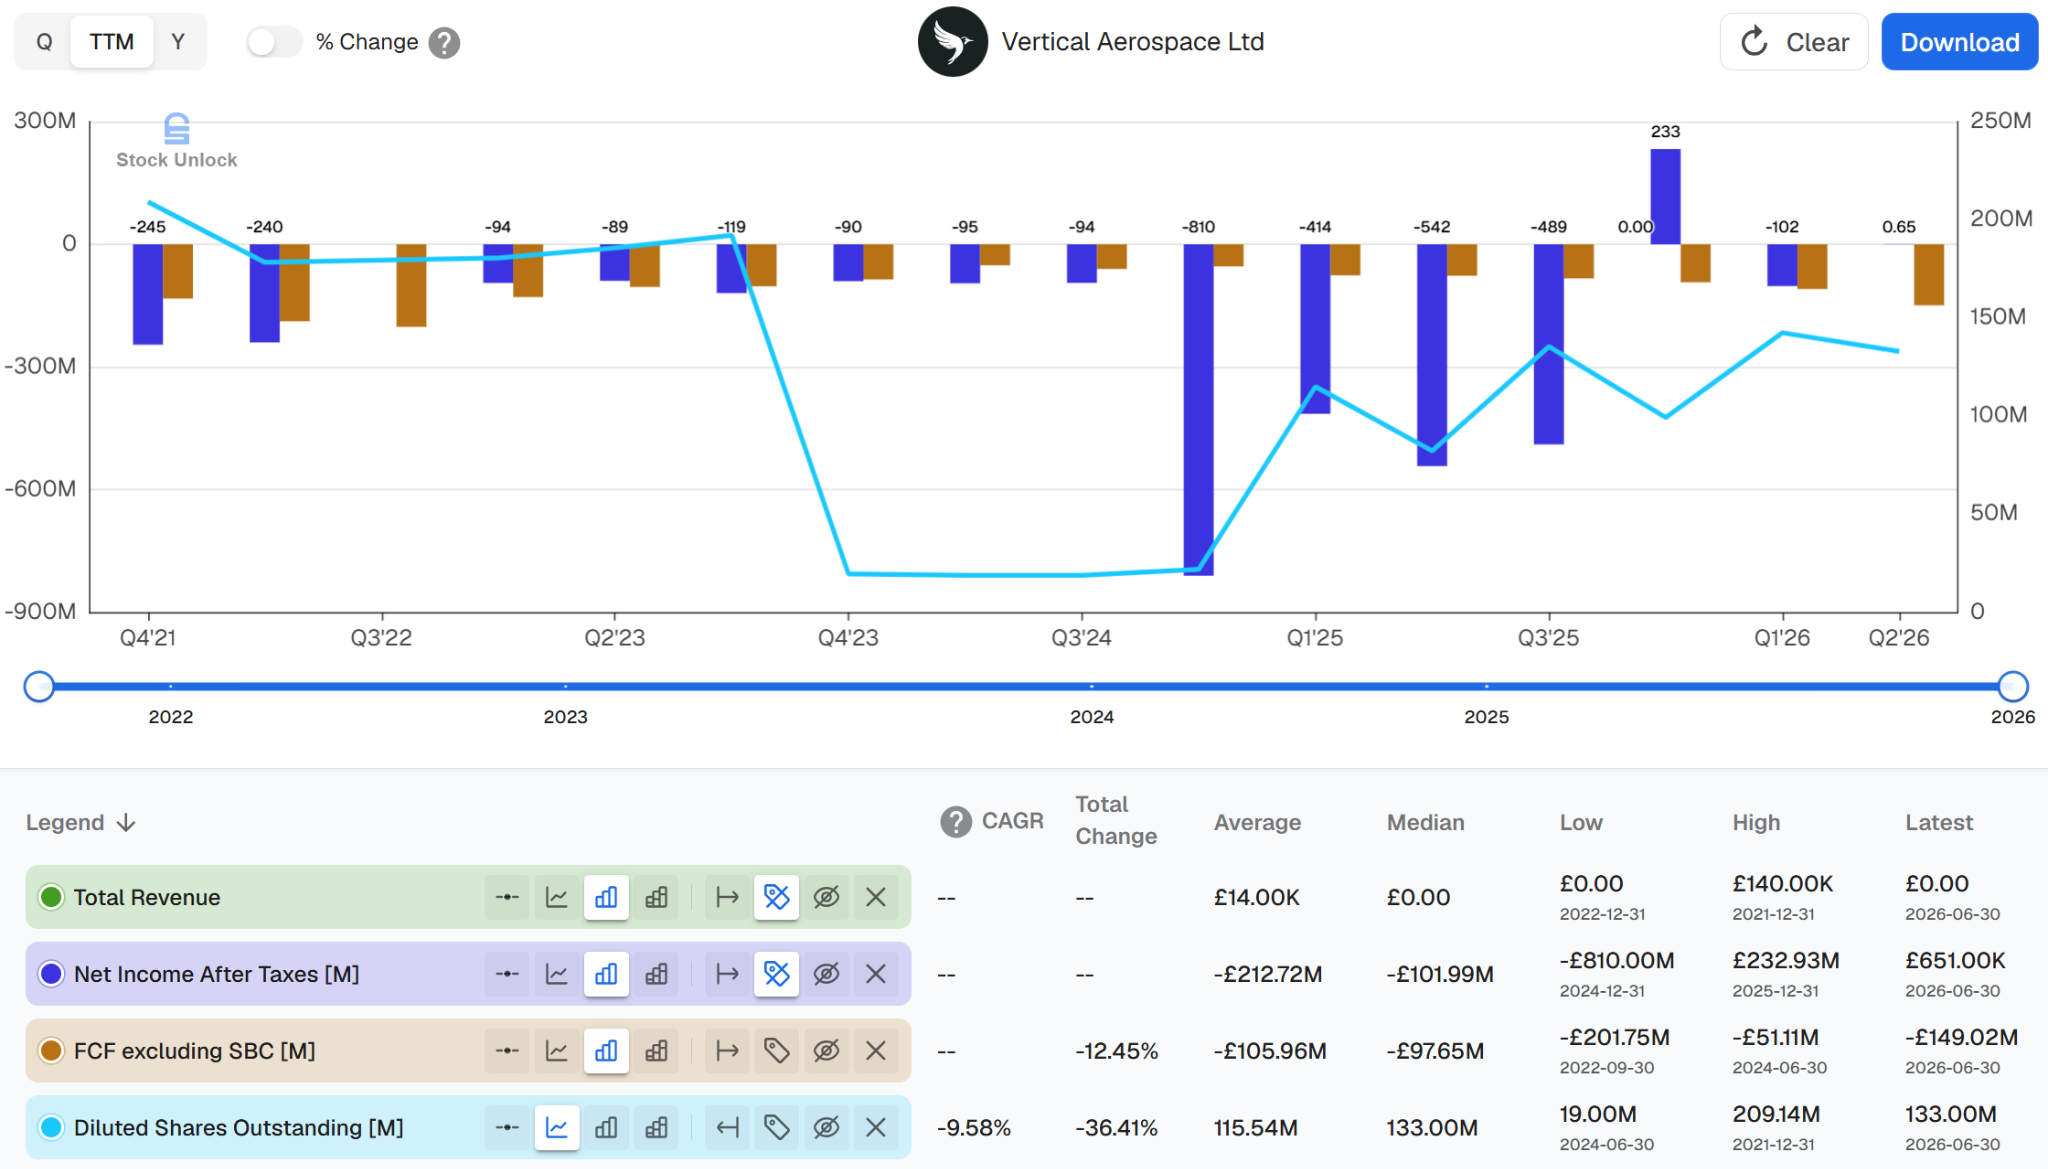
Revenue trend: The only profit is a purely accounting one, a non-cash gain from remeasuring the convertible notes at fair value. The dilution figures are also inaccurate, because the company went through a reverse split.
Data Analysis:
| Ticker | EVTL | |
| Next Earnings | 11-02 | |
| Share Price | 0.63 | |
| Diluted Shares | 133.00 M | |
| Market Cap | 83.79 M | # Far too small. |
| Revenue | 0.00 M | |
| Earning | 0.9 M | |
| PS | INF | |
| PE | 94.26 | |
| Cash | 66.87 M | |
| FCF (-SBC) | -200.6 M | |
| Cash Runway | 0.33 | |
| PFCF | -0.42 | |
| Dilution 3Y | ||
| Dilution 1Y | 61.62% | |
| Short Float % | 9.68% | |
| Days to Cover | 3.41 | |
| Borrow Fee | 0.95% | |
| Reasonable Market Cap | 135.5 M | # Total tangible assets. |
| Profit Potential | -61.77% | |
| Loss Intensity | -119.15% | |
| Confidence It Is Not Viable 0-10 | 3 | |
| Has Crash Catalyst 0-10 | 6 | |
| No Short-Squeeze Risk 0-10 | 7 |
External Views
2026-06-28 Failed eVTOL Company Entering Hyper-Dilution $EVTL - Broken Business Models
- Breaking down the $850M: a $50M ATM + a $50M convertible extension + Yorkville's $250M convertible preferred + a $500M equity line of credit (ELOC)
- Yorkville's conversion price is 96% of the lowest VWAP over the 5 days before conversion, and the ELOC is 97% of that day's VWAP — whether the stock rises or falls, it always takes its shares at a discount
- Yorkville is not a long-term investor, it is a "share distributor": it takes the 3% spread and dumps the stock on retail right away; its client history includes Plug Power, Lordstown, Faraday Future, DJT
Company-Specific Analysis and Research
Current view: I am late. The market cap is under $0.1B now, it is heading for bankruptcy, and the borrow fee is cheap on top of that. I have not done much in-depth research or study, so I am just putting on a tiny short casually.
Working title: An electric vertical take-off and landing passenger aircraft
Current decision: Hold the -0.07% position. I have not done deep research.