Contents
Key Summary
2026-09-02 Current view: Revenue growth has stalled completely, and the earnings that never matched the valuation in the first place are still falling. EV competition is fierce, so a high gross margin is hard to hold. Energy storage and humanoid robots are both losing the competition against China. Autonomous driving, on the other hand, does have real potential. On the whole the company as it stands cannot support its 1.41T market cap and 370 PE. The market cap is severely overvalued, so there is room to profit from a short, and it also helps hedge overall market and AI risk.
2026-09-02 Current decision: Hold the position at -4.59%. The company's market cap is severely overvalued, so there is room to profit from a short, and it also helps hedge overall market and AI risk.
2026-09-02 Current Position:
| Ticker | Total Shares | Average Cost | Current Price | Gain | Return | Exposure | Weight |
|---|---|---|---|---|---|---|---|
| TSLA | -200.00 | 436.35 | 356.09 | 16,052.00 | 18.39% | -71,218.00 | -4.59% |
2026-09-02 Trade Record:
| Date | Ticker | Action | Shares | Total | Execution Price | Weight Before | Weight After |
|---|---|---|---|---|---|---|---|
| 2024-06-26 | TSLA | Buy | 53.00 | -10,411.09 | 196.44 | ||
| 2024-12-13 | TSLA | Sell | -53.00 | 22,919.20 | 432.44 | ||
| 2025-04-07 | TSLA | Short | -1.00 | 230.45 | 230.45 | ||
| 2025-04-09 | TSLA | Short | -2.00 | 461.10 | 230.55 | ||
| 2025-04-09 | TSLA | Short | -5.00 | 1,297.55 | 259.51 | ||
| 2025-05-12 | TSLA | Short | -8.00 | 2,542.16 | 317.77 | ||
| 2025-05-27 | TSLA | Short | -5.00 | 1,814.20 | 362.84 | ||
| 2025-06-16 | TSLA | Short | -15.00 | 4,947.15 | 329.81 | ||
| 2025-09-29 | TSLA | Cover | 8.00 | -3,580.70 | 447.59 | ||
| 2025-10-07 | TSLA | Short | -17.00 | 7,457.90 | 438.70 | ||
| 2025-10-23 | TSLA | Short | -17.00 | 7,569.93 | 445.29 | ||
| 2025-10-27 | TSLA | Short | -11.00 | 5,007.75 | 455.25 | ||
| 2025-11-03 | TSLA | Short | -11.00 | 5,156.80 | 468.80 | ||
| 2025-12-18 | TSLA | Short | -41.00 | 19,998.98 | 487.78 | ||
| 2026-01-26 | TSLA | Short | -100.00 | 43,954.70 | 439.55 | ||
| 2026-01-27 | TSLA | Cover | 125.00 | -54,080.00 | 432.64 | ||
| 2026-01-27 | TSLA | Short | -100.00 | 43,316.20 | 433.16 |
2026-09-02 Cumulative P/L:
| Ticker | Long P/L | Short P/L | Total P/L | Source | Currently Held |
|---|---|---|---|---|---|
| TSLA | 12,508 | 14,605 | 27,113 | Mixed | Yes |
2026-09-02 Technology route: Electric vehicles, autonomous driving, energy storage, humanoid robots.
- Electric vehicles: They do this well, but in the global market Chinese-made EVs are catching up hard. Protectionist policy in the US and the EU leaves Tesla some breathing room, but the margin damage was unavoidable all the same.
- Autonomous driving: This is the piece we are most positive on. The latest hardware plus the latest FSD really is very good now. In the US, Tesla's autonomous driving is currently one of a kind, and the market is enormous. But over the very long term, we do not think the monopoly lasts. Autonomous driving ends up commoditized, and like shipping and airlines it turns into a bulk-commodity business where the only thing left to compete on is price.
- Energy storage: Even with the current US policy backdrop of pulling supply chains back home, we still do not believe in building battery and solar manufacturing on US soil. We think the competitive advantage sits in China.
- Humanoid robots: The pie drawn here is huge and the actual progress is far too thin. All kinds of Chinese companies have gushed out in this area, while Tesla's progress has been very limited. Compared with China, the US also lacks the supply chain advantage. We are not positive on it.
2026-09-02 Danger signals: # Signals that should make us re-examine our view and the risks.
- Company revenue and earnings start growing steadily again.
- Robotaxi starts rolling out at scale and contributes meaningful revenue to the company.
Complete Notes
Created the Note
Trade Record:
| Date | Ticker | Action | Shares | Total | Execution Price | Weight Before | Weight After |
|---|---|---|---|---|---|---|---|
| 2024-06-26 | TSLA | Buy | 53.00 | -10,411.09 | 196.44 | ||
| 2024-12-13 | TSLA | Sell | -53.00 | 22,919.20 | 432.44 | ||
| 2025-04-07 | TSLA | Short | -1.00 | 230.45 | 230.45 | ||
| 2025-04-09 | TSLA | Short | -2.00 | 461.10 | 230.55 | ||
| 2025-04-09 | TSLA | Short | -5.00 | 1,297.55 | 259.51 | ||
| 2025-05-12 | TSLA | Short | -8.00 | 2,542.16 | 317.77 | ||
| 2025-05-27 | TSLA | Short | -5.00 | 1,814.20 | 362.84 | ||
| 2025-06-16 | TSLA | Short | -15.00 | 4,947.15 | 329.81 | ||
| 2025-09-29 | TSLA | Cover | 8.00 | -3,580.70 | 447.59 | ||
| 2025-10-07 | TSLA | Short | -17.00 | 7,457.90 | 438.70 | ||
| 2025-10-23 | TSLA | Short | -17.00 | 7,569.93 | 445.29 | ||
| 2025-10-27 | TSLA | Short | -11.00 | 5,007.75 | 455.25 | ||
| 2025-11-03 | TSLA | Short | -11.00 | 5,156.80 | 468.80 | ||
| 2025-12-18 | TSLA | Short | -41.00 | 19,998.98 | 487.78 | ||
| 2026-01-26 | TSLA | Short | -100.00 | 43,954.70 | 439.55 | ||
| 2026-01-27 | TSLA | Cover | 125.00 | -54,080.00 | 432.64 | ||
| 2026-01-27 | TSLA | Short | -100.00 | 43,316.20 | 433.16 |
Cumulative P/L:
| Ticker | Long P/L | Short P/L | Total P/L | Source | Currently Held |
|---|---|---|---|---|---|
| TSLA | 12,508 | 14,605 | 27,113 | Mixed | Yes |
Current Position:
| Ticker | Total Shares | Average Cost | Current Price | Gain | Return | Exposure | Weight |
|---|---|---|---|---|---|---|---|
| TSLA | -200.00 | 436.35 | 356.09 | 16,052.00 | 18.39% | -71,218.00 | -4.59% |
Company-Specific Analysis and Research
Technology route: Electric vehicles, autonomous driving, energy storage, humanoid robots.
- Electric vehicles: They do this well, but in the global market Chinese-made EVs are catching up hard. Protectionist policy in the US and the EU leaves Tesla some breathing room, but the margin damage was unavoidable all the same.
- Autonomous driving: This is the piece we are most positive on. The latest hardware plus the latest FSD really is very good now. In the US, Tesla's autonomous driving is currently one of a kind, and the market is enormous. But over the very long term, we do not think the monopoly lasts. Autonomous driving ends up commoditized, and like shipping and airlines it turns into a bulk-commodity business where the only thing left to compete on is price.
- Energy storage: Even with the current US policy backdrop of pulling supply chains back home, we still do not believe in building battery and solar manufacturing on US soil. We think the competitive advantage sits in China.
- Humanoid robots: The pie drawn here is huge and the actual progress is far too thin. All kinds of Chinese companies have gushed out in this area, while Tesla's progress has been very limited. Compared with China, the US also lacks the supply chain advantage. We are not positive on it.
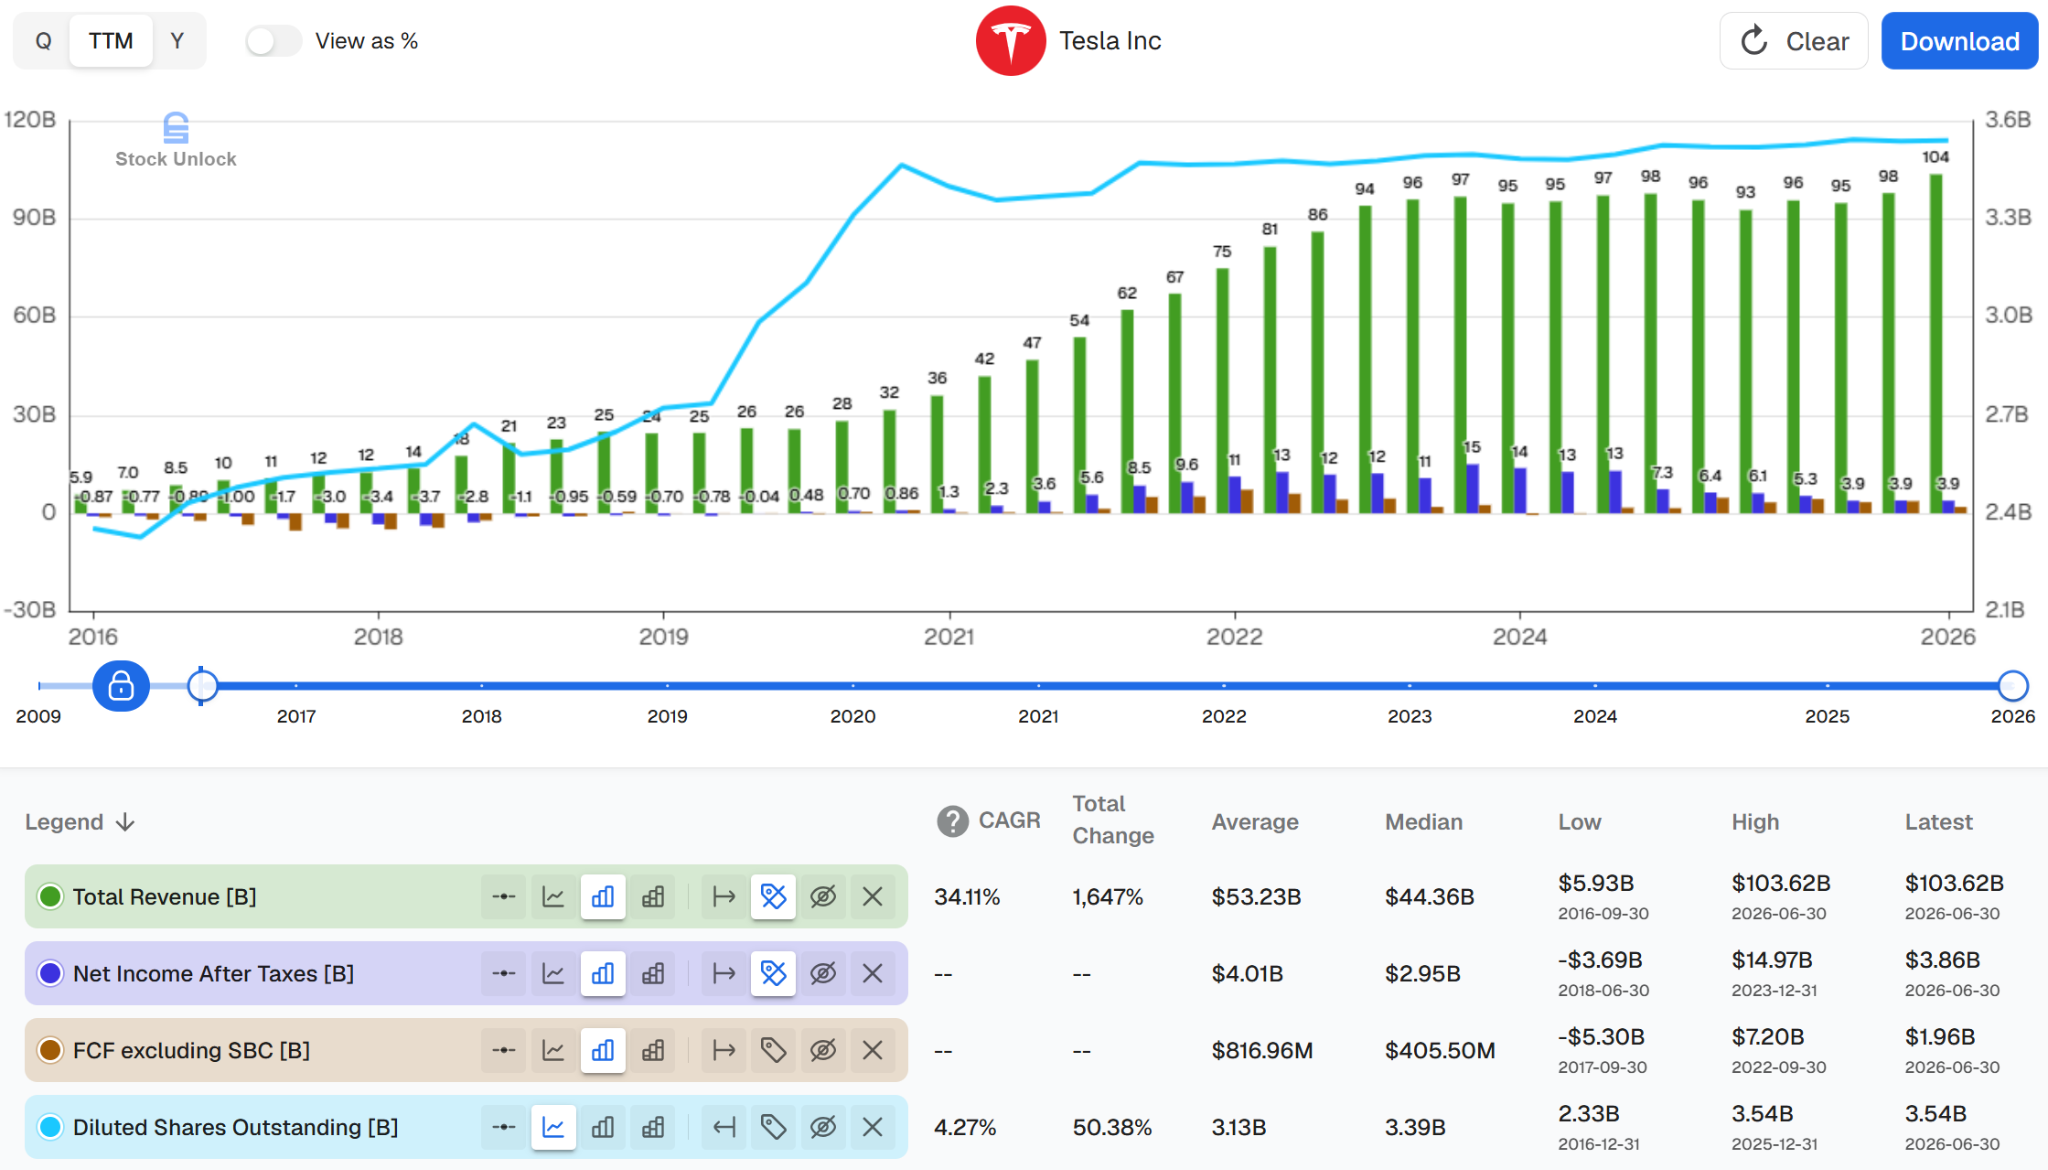
Revenue trend: Revenue growth has stalled, the earnings that never matched the valuation in the first place have dropped quite a bit more, and the equity is still being diluted.
Stock community:
Current view: Revenue growth has stalled completely, and the earnings that never matched the valuation in the first place are still falling. EV competition is fierce, so a high gross margin is hard to hold. Energy storage and humanoid robots are both losing the competition against China. Autonomous driving, on the other hand, does have real potential. On the whole the company as it stands cannot support its 1.41T market cap and 370 PE. The market cap is severely overvalued, so there is room to profit from a short, and it also helps hedge overall market and AI risk.
Working title: Revenue growth has stalled, earnings keep shrinking, and the PE is still absurdly high
Danger signals: # Signals that should make us re-examine our view and the risks.
- Company revenue and earnings start growing steadily again.
- Robotaxi starts rolling out at scale and contributes meaningful revenue to the company.
Current decision: Hold the position at -4.59%. The company's market cap is severely overvalued, so there is room to profit from a short, and it also helps hedge overall market and AI risk.